
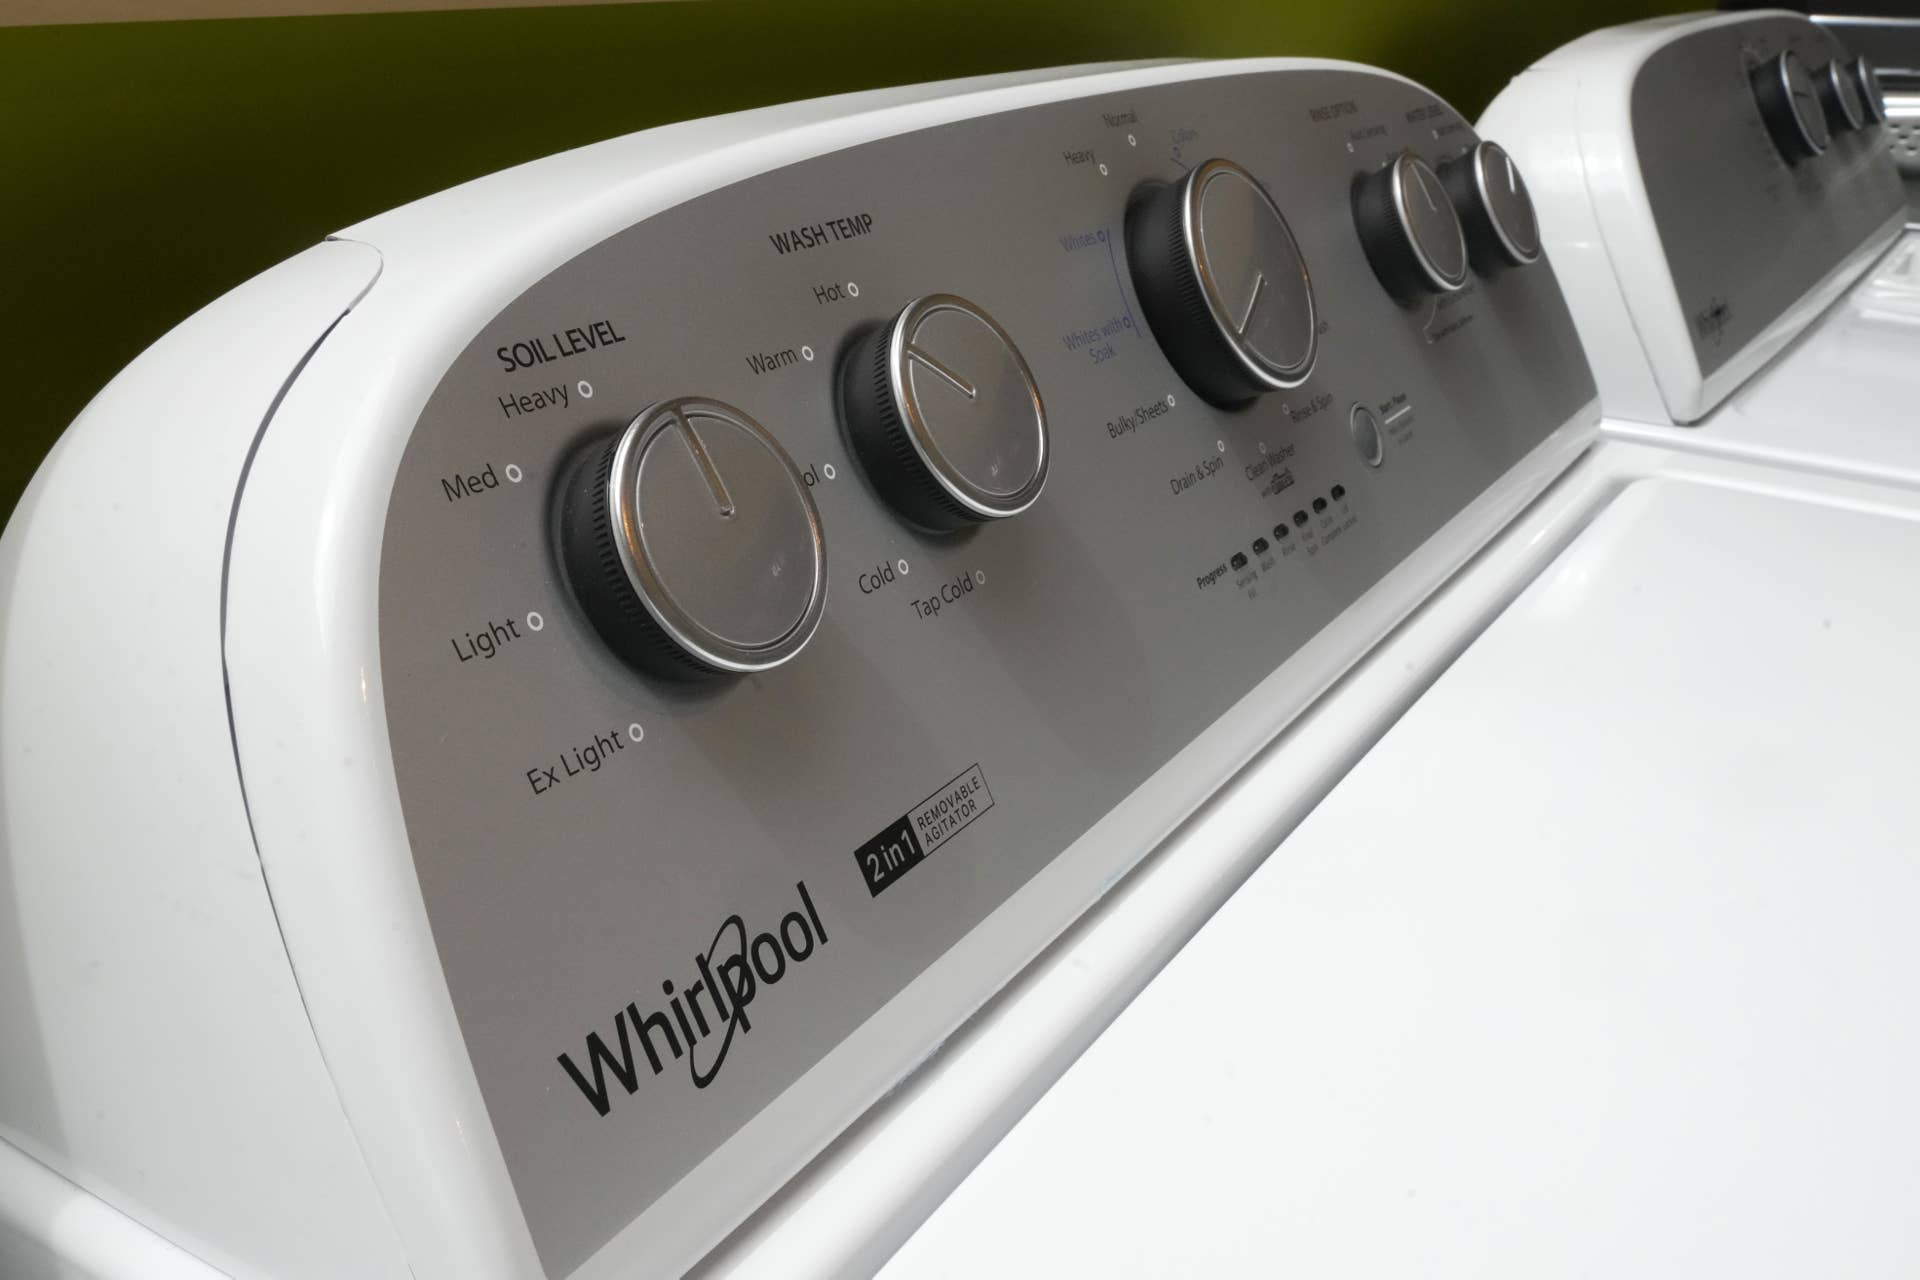
Valued at a market cap of $1.8 billion, Whirlpool stock is down 82% over the past decade. The stock is down 63% in 2026 and continues to disappoint Wall Street.
Replacement demand was the steady core of the company’s business and was the part appliance makers could always count on.
Longbow Research analyst David MacGregor put it at roughly 55% to 60% of total demand during Whirlpool’s (WHR) Q3 earnings call.
Lately, even that core has started to wobble, and Wall Street noticed. Goldman Sachs responded with a note that shows how analysts now see the road ahead.
Appliance shoppers hit pause
In Q3 of 2026, Whirlpool reported net sales of $3.7 billion, down 8.8% year over year due to soft demand in North America.
Demand across the North American appliance industry fell 3.3% in the third quarter. Whirlpool expects industry demand to finish the year down about 5%.
Also Read: McDonald’s, Whirlpool CEOs flag the same concern on the economy
CEO Marc Bitzer explained where the drop is coming from. The market is now mostly a replacement market, he said, and the decline is tied to discretionary purchases.
Discretionary purchases, like upgrades and premium models, are where Whirlpool benefits from higher-margin products.
When shoppers only buy what they must, the company sells more basic models at thinner margins.
Some households are also choosing to repair instead of replace. Bitzer said he has seen this before and pointed to the 2008 financial crisis, when shoppers held back on items like dishwashers or a second appliance.
Goldman cuts Whirlpool stock price target
Goldman Sachs (GS) lowered its price target on Whirlpool to $35 from $41, according to TheFly.com. The firm kept its Neutral rating after the third-quarter earnings miss and the guidance cut.
The research note says consumers are delaying appliance purchases because of the macro backdrop, which includes replacement units, thereby impacting volumes and product mix in North America.
However, Goldman said that as operating conditions get tougher, Whirlpool’s focus on protecting profitability and liquidity should help position it for an eventual recovery.
Related: Goldman Sachs sends a stern warning to stock market investors
Given consensus estimates compiled by TIKR, Whirlpool is projected to improve free cash flow from $78 million in 2025 to $228.7 million in 2028.
If the stock is priced at 8.33x forward FCF, which is in line with its five-year average, it could gain 5% over the next 15 months.
Out of the nine analysts covering WHR stock, six recommend “Hold” and three recommend “Sell.”
The average Whirlpool stock price target is $27, 1.5% below the current price.
Price hikes are the big bet
Whirlpool is trying to price its way back to healthier margins.
It raised prices in April and July, while retail price data shows gains of 8% to 9% over January 2025 levels.
Bitzer admitted the company “had to course correct a little bit” in the third quarter after aiming very high in June and July.
Whirlpool announced a 7% increase effective Nov. 1 in Canada and Dec. 3 in the U.S., while Latin America will see increases of up to 10%.
One analyst asked whether rivals had followed Whirlpool’s summer increases. Bitzer said he could not speak for competitors, but noted he had seen competitor price moves in October.
More retail:
- Kroger cuts discounts, promises pricing changes
- Walmart gets aggressive when it comes to holiday sales
- Costco copies a popular Trader Joe’s collectible
He added that Whirlpool will lead when costs justify it and said market share has held steady all year, helped by new products.
Several factors impacted profit margins for Whirlpool in Q3:
- Price increases in North America and Latin America more than covered weaker product mix, adding about 250 basis points.
- Tariffs pulled margin down by about 225 basis points, mainly from new Section 232 tariffs in the U.S.
- Higher steel, resin, and base metal costs took away another 75 basis points.
Steel is a major cost pressure. Bitzer said North American steel prices rose about 50% over the past 12 months.
He called that increase disconnected from reality, since iron ore and international steel prices fell. Whirlpool has locked in two of its three long-term steel contracts at what he called fair prices.
Whirlpool’s own cost cuts are the other half of the plan.
Plant upgrades, supply chain changes, and a 25% cut in local distribution centers add up to $290 million in structural savings, most of which arrives in 2027.
In Q3, Whirlpool reported a loss of $0.21 per share, while the EBIT (earnings before interest, and tax) margin stood at 2.6%, an increase of 80 basis points sequentially, but lower than consensus estimates.
Here is what the company now expects for 2026:
- Organic revenue down about 1.5%
- Ongoing EBIT margin between 2% and 2.2%
- Free cash flow of about $300 million, or roughly 2% of net sales
- Year-end net debt below $4.5 billion, better than the earlier target of under $5 billion
- Gross cost savings of about $250 million, with net savings below $150 million
Cash and debt give Whirlpool a cushion
The third quarter was rough on cash. Whirlpool burned through about $1.1 billion more than it generated.
Part of the hit came from Grupo Casas Bahia, a major Brazilian retailer that filed for bankruptcy reorganization in August. Whirlpool had not yet collected money tied to that retailer.
Bitzer said the fourth quarter is typically when cash flow flips from negative or low to positive.
Whirlpool expects to collect about $100 million of the Casas Bahia money, plus most of its related insurance payments.
CFO Roxanne Warner said the company has more than $3 billion of available liquidity, and Bitzer said the revolving credit line has not been touched since August.
Bitzer was candid about the trade-off. “I’m prepared to carry a little bit too much liquidity around us because we’re living in a very uncertain environment.”
Bloomberg / Getty Images
My take on Whirlpool stock
I read Goldman’s Neutral rating as fair.
The 2027 setup has three things going for it:
- First, price increases carry over. Bitzer said Whirlpool exits the year with several points of positive pricing heading into 2027.
- Second, about $290 million in structural cost savings arrive, mostly next year.
- Third, inventories are low at both Whirlpool and its retailers, so the company does not need to cut production further.
The small appliance business adds a lift. It posted an 18.6% EBIT margin, and its October U.S. orders were up about 40%.
But the plan needs a lot to go right. Prices must not weigh heavily on product demand and commodities prices should cool off.
Further, shoppers who are putting off a new washer or dishwasher cannot trade down to cheaper models in large numbers.
Bitzer put the priority plainly. “Our clear focus for Q4 and also for next year is margin expansion, period,” he said.
Whirlpool will share 2027 guidance on its January call. That is when I will judge whether this waiting room has a door out.
More Stocks News
- Landstar stock plunges 17.8% on insurance costs and EPS miss
- Breakthrough cancer vaccine catches Wall Street’s attention
- Boeing CEO admits 737 ramp taking longer than hoped
- Down 82% from all-time highs, can PayPal stock finally recover in 2027?